If you inherited a rental or kept your old home as one, you have more options than "hold" or "sell and get taxed." Here's what most owners never hear.
Maybe you kept your old home as a rental after buying your next one, or you inherited a property and held onto it because the numbers just made sense. Either way, you’ve probably wondered whether holding on is still right, or whether it’s quietly turning into a hassle. Most owners never hear the answer, and it can change how you see both that rental and your retirement.
A couple I worked with had inherited a home that happened to be a rental. They never set out to be landlords, unlike so many families across the Bay Area. It was paid off and brought in a few thousand a month, so keeping it felt obvious for years. What wore on them was every tenant turnover, the cleanup, the screening, and the long wait for rent to restart. It was a slow hassle, not a single crisis. When their tenants gave notice, they almost sold on instinct, then hesitated. They feared they were foolish to sell, that a big remodel loomed, and that capital gains would take a brutal cut. Rather than guess their way through it again, they called me.
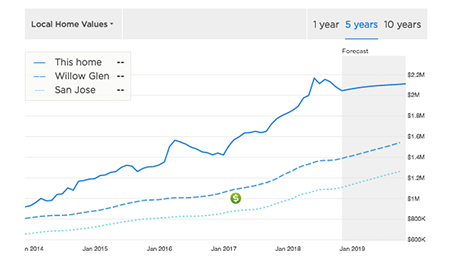
You have far more than two options. Most owners believe the only choices are to keep collecting rent or to sell and lose a big chunk of equity to taxes. The real menu is wider. We started with honest numbers: what the property was truly worth, and what it actually earned after taxes, insurance, repairs, and management. From there we compared three real paths side by side. They could re-rent it, sell it outright, or trade the equity into something better. Seeing the options laid out cleanly took away most of the fear, because fear usually comes from not knowing them.
“They didn’t lose the property or the income; they upgraded both.”
Both fears are usually smaller than they look. The first fear is an expensive remodel before anyone pays a fair price. When we ran that couple’s numbers, a remodel wasn’t worth it, which is more common than owners expect. The second fear is that selling means a vacant, torn-up house and a rushed move-out. Here is where most agents stay quiet. Builders and investors often prefer a property with tenants in place, because their permitting can take months. A tenant finishing a lease costs them nothing, and it saves you the whole off-market cleanup-and-vacancy cycle. We sold this couple’s home with tenants still in place, for a premium over a traditional vacant sale, and with no remodel.
A 1031 exchange lets you trade, not cash out. Most owners assume selling means a painful hit on capital gains and depreciation recapture. A 1031 exchange can let you move your equity into another property while deferring those gains, rather than handing them to the IRS. For this couple, it reframed the whole decision.
Instead of cashing out and getting taxed, we traded their equity into newer properties where the numbers made more sense, and their income grew substantially. One of them left a part-time job, and now they travel regularly. It’s all funded by the asset they once thought of as just the rental. A 1031 carries strict rules and timelines, and everyone’s taxes differ, so walk through it carefully with me and your tax professional. When it fits, it can be a real turning point.
Start with an honest read on the numbers. If you own a property you never set out to own, your options are usually wider and better than you fear. You don’t have to white-knuckle every turnover or lose a fortune to taxes to move on. The first step is simply knowing what your rental is really worth today and what it’s actually netting you once every cost is counted. Once the real figures are in front of you, the right path tends to come into focus. That matters across a Bay Area market that rewards owners who plan ahead, the way our buyers and sellers do.
I’d love to give you a free, private review of your rental. We’ll take an honest look at what it’s worth, what it earns, and whether keeping, selling, or trading it best serves your next chapter. Call or text me at 408-317-0506, email me at Brett@TheRealExperts.com, or visit therealexperts.com. You’ll come away knowing exactly where you stand, with nothing you’re obligated to act on. (This is general information, not tax or legal advice; please consult a qualified tax professional about your situation.)